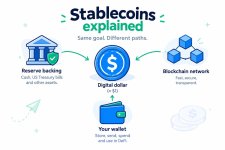
If you have spent time in crypto space, you have probably seen and heard of USDT, USDC, DAI, USDe, PYUSD and FDUSD.
They all aim to maintain a relatively stable value, usually around $1. But they do not all work the same way.
Some rely on cash and US Treasury securities. Others use crypto collateral, smart contracts or derivatives strategies.
Think of them as six different ways to create a digital dollar. They may look similar in your wallet, but the systems behind them are very different.
Let's break them down.
1. What exactly is a stablecoin?
A stablecoin is a cryptocurrency designed to track the value of another asset. In this guide, we're focusing on coins designed to stay close to one US dollar.
Unlike Bitcoin, whose price can swing dramatically, a dollar-pegged stablecoin aims to maintain a value of approximately $1.
Why are they useful?
- Trading: Move out of volatile crypto without immediately converting to traditional money.
- Payments: Send digital dollars through supported blockchain networks.
- DeFi: Use stablecoins in supported lending, borrowing and liquidity protocols.
- Dollar exposure: Hold an asset linked to the US dollar, subject to exchange rates, fees and local restrictions.
But remember, 'stable' doesn't mean 'risk-free'. A stablecoin can fall below $1, lose its peg or become difficult to redeem.
There are three broad ways to understand their designs:
1. Reserve-backed: An issuer holds assets intended to cover the tokens in circulation.
2. Crypto-collateralised: A protocol uses cryptocurrency or other approved assets as collateral.
3. Synthetic: A system combines backing assets with financial strategies, such as derivatives hedging.
Source: Ethereum.org's stablecoin guide(https://ethereum.org/stablecoins/)

2. USDC: The digital dollar from Circle
USDC, issued by Circle, is designed to maintain a 1:1 value with the US dollar.
Circle backs USDC with reserves that include cash and cash-equivalent assets, such as short-term US Treasury securities. It publishes reserve information and third-party assurance reports.
You can check these through Circle's transparency page - (
 www.circle.com
).
Why use it?
USDC is used for crypto trading, payments, transfers and DeFi. Its published reserve information helps users understand what supports the token.
For example, a freelancer paid in USDC can hold it in a compatible wallet or transfer it to another supported wallet without using a traditional bank transfer for every transaction.
What are the risks?
USDC depends on Circle, its reserves, financial counterparties and redemption arrangements. Access and issuer restrictions may also apply, and its market price can temporarily move away from $1.
In short, USDC is a widely used option for people who want a dollar-pegged stablecoin with published reserve information.
Source: Circle USDC and transparency-(https://www.circle.com/transparency)
3. USDT: The crypto trading regular
USDT, commonly called Tether, is issued by Tether and aims to remain worth approximately $1.
You've probably seen trading pairs like BTC/USDT or ETH/USDT on exchanges.
Tether says USDT is backed by reserves that include US Treasury securities, cash and cash equivalents, alongside other disclosed assets. The exact composition can change, so always check the latest reports.
Official source: Tether's transparency page - (https://tether.to/transparency/)
Why use it?
USDT has extensive use across crypto trading markets and is supported by many exchanges and wallets.
Imagine selling your ETH but wanting to wait before buying another asset. You might convert the proceeds into USDT and use it for another trade later.
What are the risks?
USDT depends on the quality and liquidity of its reserves, Tether's redemption arrangements and market confidence. Not every exchange or wallet offers direct redemption for dollars.
Summarily, USDT is particularly useful to understand if you trade crypto rather frequently.
4. DAI: The stablecoin built around collateral
DAI takes a different approach.
Developed within the MakerDAO ecosystem, now known as Sky Protocol, DAI uses a protocol-based system involving collateral, smart contracts and economic incentives to help maintain its dollar peg.
Imagine you own ETH but don't want to sell it. A collateralised borrowing system can let you lock up eligible assets and generate DAI against them.
For example, you might deposit $150 worth of collateral to borrow 100 DAI in a simplified scenario. The extra collateral provides a buffer if the market falls. Actual borrowing limits depend on protocol rules and the assets involved.
If collateral loses too much value, the position may be liquidated to help cover the debt.
DAI's backing system has evolved over time and can include different types of assets, not just cryptocurrency.
Why use it?
DAI is useful for people exploring decentralised finance, including borrowing, lending and other on-chain applications.
What are the risks?
Risks include collateral crashes, liquidation, smart contract vulnerabilities, governance decisions and exposure to assets or counterparties within its backing system.
In short, DAI helps explain how collateral and smart contracts can support a digital dollar.
Source: Sky Protocol documentation - (https://developers.skyeco.com/protocol/tokens/dai/)
5. USDe: Ethena's synthetic dollar
USDe is issued through Ethena and is described as a synthetic dollar. It is not simply a conventional stablecoin backed by cash reserves.
Ethena's model involves backing assets, including crypto assets and stablecoins, alongside derivatives positions designed to offset price exposure.
This strategy is called 'delta hedging'.
Imagine a system holds ETH while also holding a short derivatives position against ETH. If ETH's price falls, the short position may gain value while the ETH loses value. When appropriately structured, the positions can offset some of each other's price movements.
However, this isn't a perfect shield. Funding costs, liquidity problems, exchange failures and other market events can disrupt the strategy.
Why use it?
USDe offers another way to access dollar-linked value in crypto and is used in supported trading and DeFi applications.
Don't confuse USDe with sUSDe. They are different tokens with different functions; holding USDe alone does not automatically mean earning a yield.
What are the risks?
USDe has additional risks tied to derivatives venues, hedging, custody, liquidity, smart contracts and the ability to maintain its peg during market stress.
In short, USDe is interesting, but its mechanics are more complex than those of a conventional reserve-backed stablecoin.
Source: Ethena documentation - https://docs.ethena.fi/

6. PYUSD: PayPal's dollar-linked stablecoin
PYUSD stands for PayPal USD. It is branded by PayPal and issued by Paxos.
PYUSD is designed to maintain a 1:1 value with the US dollar. Paxos says it is backed by US dollar deposits, US Treasury securities and cash equivalents, and publishes reserve reports.
Sources: Paxos PYUSD documentation -(https://docs.paxos.com/guides/stablecoin/pyusd) | [Paxos PYUSD overview](https://www.paxos.com/pyusd)
Why use it?
PYUSD is designed for payments and can be used in supported wallets, exchanges and blockchain applications. It may interest businesses exploring digital payments.
However, don't assume every PayPal account, country or service supports every PYUSD feature. Availability depends on location and product terms.
What are the risks?
PYUSD depends on Paxos's reserve management, redemption arrangements and supporting infrastructure. Network fees and platform restrictions also matter.
In short, PYUSD connects an established payments brand with blockchain-based money.
7. FDUSD: First Digital USD
FDUSD is a dollar-pegged stablecoin from the First Digital ecosystem.
Its issuer describes it as backed by cash and cash-equivalent assets intended to support redemption at approximately $1 per token. Users should check current reserve disclosures rather than rely on old reports.
Official source: First Digital Labs transparency page - (https://www.firstdigitallabs.com/transparency)
Why use it?
FDUSD has been used in crypto trading and is available on supported exchanges and networks. It can be an option for traders whose platforms support it.
What are the risks?
Its stability depends on the issuer, reserve assets, custody and redemption arrangements. Its usefulness also depends on liquidity and platform support.
Summarily, FDUSD is another reserve-backed alternative, but one should check its availability and current disclosures before using it.
8. The six stablecoins compared
No single option is automatically best for everyone. Reserve-backed tokens, collateral-based protocols and synthetic dollars have different dependencies and risks.

9. How do you choose one?
Your choice depends on what you want to do.
- For trading: Check exchange support, liquidity, trading pairs and fees. USDT and USDC are common options on many platforms.
- For payments: Check whether the sender, receiver and payment provider support the same token and network. PYUSD may suit certain payment flows.
- For DeFi: DAI is worth exploring for collateralised borrowing. USDe is worth studying if you're interested in synthetic dollars and hedging.
- For holding dollar-linked value: Check the issuer, backing model, redemption rules and the cost of converting from your local currency.
Also, pay attention to the blockchain. USDC on Ethereum and USDC on another network are not automatically interchangeable in every wallet or service.
Before transferring, verify the token contract address, network and receiving platform. Sending funds through an unsupported network can lead to losses.
10. Five risks every beginner should know
1. Depegging: A stablecoin can trade below or above $1.
2. Reserve risk: Backing assets, custody and redemption arrangements matter.
3. Smart contract risk: Code vulnerabilities can affect tokens and DeFi protocols.
4. Liquidity risk: You may not be able to sell at exactly $1 when markets are stressed.
5. Operational risk: Fake tokens, malicious contracts and incorrect network transfers can cost you money.
A stablecoin reduces one kind of uncertainty: price volatility is what it is designed to limit. It does not eliminate every risk in crypto.
Conclusion:
Understand what sits behind the dollar
USDC and USDT are widely used reserve-backed stablecoins. DAI relies on a collateral and protocol system. USDe uses a synthetic-dollar strategy involving derivatives. PYUSD brings a payment-focused approach, while FDUSD offers another reserve-backed option.
They share a target, but the mechanisms behind them are different.
Before choosing one, ask three questions: What backs it? Who or what manages it? How can I use or redeem it?
You don't need to know every technical detail to get started. Just do your research and never assume that a $1 target means zero risk.
Disclaimer: This thread is for educational purposes only, not financial advice. Stablecoins can lose their peg and result in financial losses. Always review current documentation, issuer terms and local requirements before using them.
They all aim to maintain a relatively stable value, usually around $1. But they do not all work the same way.
Some rely on cash and US Treasury securities. Others use crypto collateral, smart contracts or derivatives strategies.
Think of them as six different ways to create a digital dollar. They may look similar in your wallet, but the systems behind them are very different.
Let's break them down.
1. What exactly is a stablecoin?
A stablecoin is a cryptocurrency designed to track the value of another asset. In this guide, we're focusing on coins designed to stay close to one US dollar.
Unlike Bitcoin, whose price can swing dramatically, a dollar-pegged stablecoin aims to maintain a value of approximately $1.
Why are they useful?
- Trading: Move out of volatile crypto without immediately converting to traditional money.
- Payments: Send digital dollars through supported blockchain networks.
- DeFi: Use stablecoins in supported lending, borrowing and liquidity protocols.
- Dollar exposure: Hold an asset linked to the US dollar, subject to exchange rates, fees and local restrictions.
But remember, 'stable' doesn't mean 'risk-free'. A stablecoin can fall below $1, lose its peg or become difficult to redeem.
There are three broad ways to understand their designs:
1. Reserve-backed: An issuer holds assets intended to cover the tokens in circulation.
2. Crypto-collateralised: A protocol uses cryptocurrency or other approved assets as collateral.
3. Synthetic: A system combines backing assets with financial strategies, such as derivatives hedging.
Source: Ethereum.org's stablecoin guide(https://ethereum.org/stablecoins/)
2. USDC: The digital dollar from Circle
USDC, issued by Circle, is designed to maintain a 1:1 value with the US dollar.
Circle backs USDC with reserves that include cash and cash-equivalent assets, such as short-term US Treasury securities. It publishes reserve information and third-party assurance reports.
You can check these through Circle's transparency page - (
Transparency & Stability | Circle
Circle-issued stablecoins — USDC and EURC — are designed for stability. Learn more about our stablecoin backing and reserve transparency.
www.circle.com
Why use it?
USDC is used for crypto trading, payments, transfers and DeFi. Its published reserve information helps users understand what supports the token.
For example, a freelancer paid in USDC can hold it in a compatible wallet or transfer it to another supported wallet without using a traditional bank transfer for every transaction.
What are the risks?
USDC depends on Circle, its reserves, financial counterparties and redemption arrangements. Access and issuer restrictions may also apply, and its market price can temporarily move away from $1.
In short, USDC is a widely used option for people who want a dollar-pegged stablecoin with published reserve information.
Source: Circle USDC and transparency-(https://www.circle.com/transparency)
3. USDT: The crypto trading regular
USDT, commonly called Tether, is issued by Tether and aims to remain worth approximately $1.
You've probably seen trading pairs like BTC/USDT or ETH/USDT on exchanges.
Tether says USDT is backed by reserves that include US Treasury securities, cash and cash equivalents, alongside other disclosed assets. The exact composition can change, so always check the latest reports.
Official source: Tether's transparency page - (https://tether.to/transparency/)
Why use it?
USDT has extensive use across crypto trading markets and is supported by many exchanges and wallets.
Imagine selling your ETH but wanting to wait before buying another asset. You might convert the proceeds into USDT and use it for another trade later.
What are the risks?
USDT depends on the quality and liquidity of its reserves, Tether's redemption arrangements and market confidence. Not every exchange or wallet offers direct redemption for dollars.
Summarily, USDT is particularly useful to understand if you trade crypto rather frequently.
4. DAI: The stablecoin built around collateral
DAI takes a different approach.
Developed within the MakerDAO ecosystem, now known as Sky Protocol, DAI uses a protocol-based system involving collateral, smart contracts and economic incentives to help maintain its dollar peg.
Imagine you own ETH but don't want to sell it. A collateralised borrowing system can let you lock up eligible assets and generate DAI against them.
For example, you might deposit $150 worth of collateral to borrow 100 DAI in a simplified scenario. The extra collateral provides a buffer if the market falls. Actual borrowing limits depend on protocol rules and the assets involved.
If collateral loses too much value, the position may be liquidated to help cover the debt.
DAI's backing system has evolved over time and can include different types of assets, not just cryptocurrency.
Why use it?
DAI is useful for people exploring decentralised finance, including borrowing, lending and other on-chain applications.
What are the risks?
Risks include collateral crashes, liquidation, smart contract vulnerabilities, governance decisions and exposure to assets or counterparties within its backing system.
In short, DAI helps explain how collateral and smart contracts can support a digital dollar.
Source: Sky Protocol documentation - (https://developers.skyeco.com/protocol/tokens/dai/)
5. USDe: Ethena's synthetic dollar
USDe is issued through Ethena and is described as a synthetic dollar. It is not simply a conventional stablecoin backed by cash reserves.
Ethena's model involves backing assets, including crypto assets and stablecoins, alongside derivatives positions designed to offset price exposure.
This strategy is called 'delta hedging'.
Imagine a system holds ETH while also holding a short derivatives position against ETH. If ETH's price falls, the short position may gain value while the ETH loses value. When appropriately structured, the positions can offset some of each other's price movements.
However, this isn't a perfect shield. Funding costs, liquidity problems, exchange failures and other market events can disrupt the strategy.
Why use it?
USDe offers another way to access dollar-linked value in crypto and is used in supported trading and DeFi applications.
Don't confuse USDe with sUSDe. They are different tokens with different functions; holding USDe alone does not automatically mean earning a yield.
What are the risks?
USDe has additional risks tied to derivatives venues, hedging, custody, liquidity, smart contracts and the ability to maintain its peg during market stress.
In short, USDe is interesting, but its mechanics are more complex than those of a conventional reserve-backed stablecoin.
Source: Ethena documentation - https://docs.ethena.fi/
6. PYUSD: PayPal's dollar-linked stablecoin
PYUSD stands for PayPal USD. It is branded by PayPal and issued by Paxos.
PYUSD is designed to maintain a 1:1 value with the US dollar. Paxos says it is backed by US dollar deposits, US Treasury securities and cash equivalents, and publishes reserve reports.
Sources: Paxos PYUSD documentation -(https://docs.paxos.com/guides/stablecoin/pyusd) | [Paxos PYUSD overview](https://www.paxos.com/pyusd)
Why use it?
PYUSD is designed for payments and can be used in supported wallets, exchanges and blockchain applications. It may interest businesses exploring digital payments.
However, don't assume every PayPal account, country or service supports every PYUSD feature. Availability depends on location and product terms.
What are the risks?
PYUSD depends on Paxos's reserve management, redemption arrangements and supporting infrastructure. Network fees and platform restrictions also matter.
In short, PYUSD connects an established payments brand with blockchain-based money.
7. FDUSD: First Digital USD
FDUSD is a dollar-pegged stablecoin from the First Digital ecosystem.
Its issuer describes it as backed by cash and cash-equivalent assets intended to support redemption at approximately $1 per token. Users should check current reserve disclosures rather than rely on old reports.
Official source: First Digital Labs transparency page - (https://www.firstdigitallabs.com/transparency)
Why use it?
FDUSD has been used in crypto trading and is available on supported exchanges and networks. It can be an option for traders whose platforms support it.
What are the risks?
Its stability depends on the issuer, reserve assets, custody and redemption arrangements. Its usefulness also depends on liquidity and platform support.
Summarily, FDUSD is another reserve-backed alternative, but one should check its availability and current disclosures before using it.
8. The six stablecoins compared
| Stablecoin | General model | Issuer or protocol | Main distinction |
| USDC | Reserve-backed | Circle | published reserve information |
| USDT | Reserve-backed | Tether | Extensive crypto |
| DAI | Collateral-based | Sky Protocol | Smart Contracts & Collateral |
| USDe | synthetic dollar | Ethena | Derivatives hedging strategy |
| PYUSD | Reserve-backed | Paxos/ PayPal brand | Payments-focused design |
| FDUSD | Reserve-backed | First Digital Ecosystem | Alternative for supported trading platforms |
No single option is automatically best for everyone. Reserve-backed tokens, collateral-based protocols and synthetic dollars have different dependencies and risks.
9. How do you choose one?
Your choice depends on what you want to do.
- For trading: Check exchange support, liquidity, trading pairs and fees. USDT and USDC are common options on many platforms.
- For payments: Check whether the sender, receiver and payment provider support the same token and network. PYUSD may suit certain payment flows.
- For DeFi: DAI is worth exploring for collateralised borrowing. USDe is worth studying if you're interested in synthetic dollars and hedging.
- For holding dollar-linked value: Check the issuer, backing model, redemption rules and the cost of converting from your local currency.
Also, pay attention to the blockchain. USDC on Ethereum and USDC on another network are not automatically interchangeable in every wallet or service.
Before transferring, verify the token contract address, network and receiving platform. Sending funds through an unsupported network can lead to losses.
10. Five risks every beginner should know
1. Depegging: A stablecoin can trade below or above $1.
2. Reserve risk: Backing assets, custody and redemption arrangements matter.
3. Smart contract risk: Code vulnerabilities can affect tokens and DeFi protocols.
4. Liquidity risk: You may not be able to sell at exactly $1 when markets are stressed.
5. Operational risk: Fake tokens, malicious contracts and incorrect network transfers can cost you money.
A stablecoin reduces one kind of uncertainty: price volatility is what it is designed to limit. It does not eliminate every risk in crypto.
Conclusion:
Understand what sits behind the dollar
USDC and USDT are widely used reserve-backed stablecoins. DAI relies on a collateral and protocol system. USDe uses a synthetic-dollar strategy involving derivatives. PYUSD brings a payment-focused approach, while FDUSD offers another reserve-backed option.
They share a target, but the mechanisms behind them are different.
Before choosing one, ask three questions: What backs it? Who or what manages it? How can I use or redeem it?
You don't need to know every technical detail to get started. Just do your research and never assume that a $1 target means zero risk.
Disclaimer: This thread is for educational purposes only, not financial advice. Stablecoins can lose their peg and result in financial losses. Always review current documentation, issuer terms and local requirements before using them.